ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Marietta
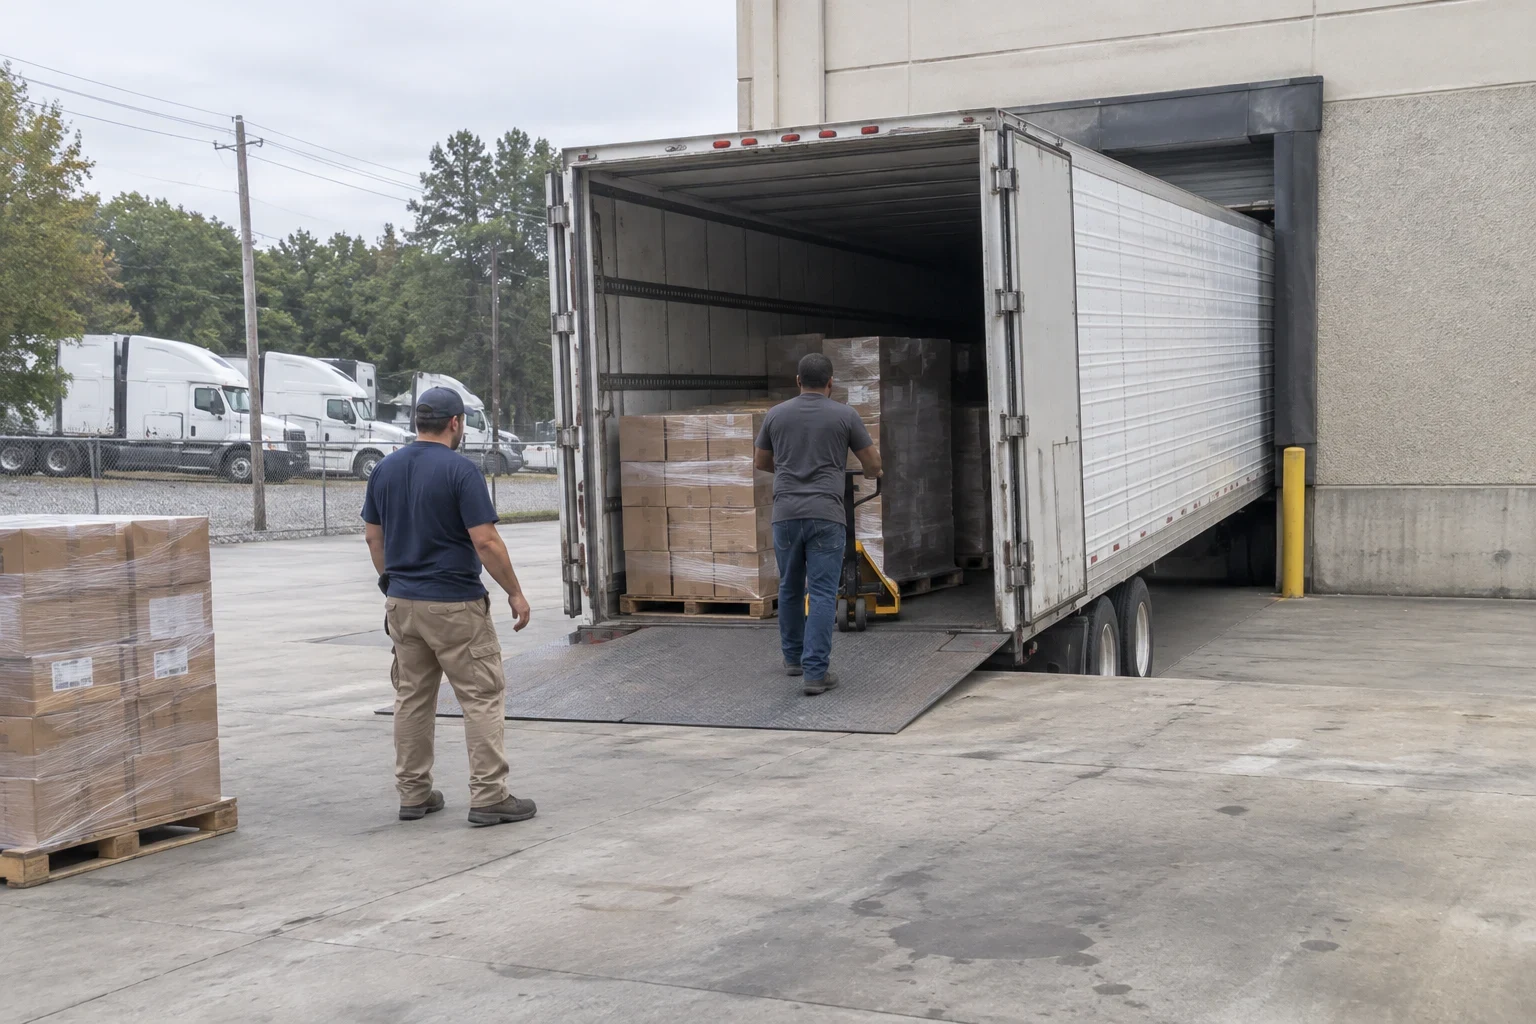
Motor truck cargo insurance pays for the freight in your care when it is damaged, lost or stolen. We build each policy around what you actually haul, how your trucks are equipped and where they sit overnight, so the coverage holds up when a claim is filed.
What cargo coverage does, and where it usually falls short
Cargo insurance protects the shipper's goods while they are on your truck. Brokers and shippers check for it before they tender a load, and most carrier packets name the cargo limit they expect to see on your certificate of insurance.
The trouble rarely shows up at the quote. It shows up months later, when a reefer unit fails or a trailer is broken into at a truck stop and the adjuster points to a commodity exclusion or an unattended vehicle clause. Two policies with the same limit can pay very differently. We read those forms line by line and tell you plainly what each one leaves out.
We have been in business 5 years, working with owner-operators and small fleets from our office in Marietta and by phone and video. Most of that work comes down to small details: the wording of a theft clause, the list of excluded commodities, how a deductible applies to a partial load.
What we look at when we set up your cargo coverage
- 01
Commodity review
We list what you haul now and what you might haul next quarter. Many cargo forms exclude or cap electronics, tobacco, alcohol, copper or pharmaceuticals, and a single excluded load can sit outside your coverage without anyone noticing.
- 02
Exclusions explained in writing
Unattended vehicle, theft and refrigeration breakdown clauses are where claims get decided. We point out each one in your policy and describe what it means for how you park, lock and run your trucks.
- 03
Limit and deductible that match your loads
Your limit should cover your most valuable typical load, not just the number a broker asked for. We set the deductible at a level your operation can absorb on a bad week.
- 04
Certificates of insurance for brokers
When a broker or shipper needs a certificate naming them, we handle it and check that the cargo limit and description match their packet before it goes out.
- 05
Fit with the rest of your policy
Cargo works alongside physical damage insurance and trailer interchange insurance. We check that a pulled trailer and the freight inside it are both accounted for, with no gap between forms.
Questions about Motor Truck Cargo Insurance?
Call(770) 762-4540Signs your cargo coverage needs a closer look
A broker rejected your certificate
If setup stalls because the limit is too low or the commodity description does not match, the policy needs adjusting before you lose more loads.
You changed what you haul
Moving from dry van general freight to produce, metals or high-value goods can bring you under an exclusion your current policy already has.
You added a reefer
Spoilage from refrigeration breakdown is not covered on every cargo form. Some include it, some sell it as an endorsement, and some require unit maintenance records.
Loads sit in the truck overnight
Drop yards, home parking and unsecured lots all matter to the theft wording. If your drivers stop loaded, we want to know where.
A past claim was denied or cut short
That is often a wording problem rather than bad luck. We can review the old policy and look for a form that treats your freight differently.
How a cargo policy comes together with us
- 1
A conversation about your operation
We start on the phone or by video. We ask about your DOT number and MC authority, your equipment, typical lanes, commodities and how loads are secured when the truck is parked.
- 2
Comparing the forms, not just the premiums
We gather quotes and read the cargo forms side by side. You see the differences in exclusions and conditions next to the price, so the choice is clear.
- 3
Walking through the policy before you bind
We go over the limit, deductible and each exclusion that could touch your freight. Questions get answered before anything is signed.
- 4
Certificates and ongoing changes
Once coverage is active, we issue certificates to your brokers and shippers. When your freight or equipment changes, we revisit the policy rather than leaving it as written.
What moves the price of cargo insurance
Cargo premiums depend mostly on what you haul and how exposed it is between pickup and delivery. Insurers price the chance of theft, spoilage and damage, so the details of your operation carry real weight. We explain which of these you can influence and which you cannot.
- Commodities
- Electronics, metals, food and other theft-prone or perishable freight cost more to insure than building materials or general dry goods.
- Limit and deductible
- A higher limit raises the premium. A higher deductible lowers it, but only makes sense if you can cover that amount on a damaged load.
- Reefer and equipment
- Refrigerated units and breakdown coverage add cost. Maintenance records on the unit can help.
- Experience and loss history
- New authority and prior cargo claims both affect pricing. A clean record over time tends to help at renewal.
- Lanes and parking
- Long-haul routes, high-theft corridors and overnight parking in unsecured lots raise the risk insurers are pricing.
Cargo insurance questions we hear often
Is motor truck cargo insurance required by law?
For most general freight carriers, there is no federal cargo filing requirement. In practice, nearly every broker and shipper requires it before tendering a load. Their packet will name the limit they expect on your certificate.
Does cargo coverage pay if my reefer unit breaks down?
Only if the policy includes refrigeration breakdown, either in the base form or as an endorsement. Some forms also require proof the unit was maintained. We check this wording on every reefer policy we place.
What happens if a load is worth more than my limit?
The policy pays up to the limit and the rest falls on you. If you occasionally haul a higher-value load, we can talk about raising the limit or arranging coverage for that shipment before you pick it up.
Is theft from a parked truck covered?
It depends on the unattended vehicle and theft clauses. Some policies require the truck to be locked with the alarm set, or parked in an enclosed or attended lot. We explain those conditions so your drivers know what they mean on the road.
I am leased on to a carrier. Do I need my own cargo coverage?
Often the motor carrier you are leased to provides cargo coverage, but not always, and some leases pass the deductible to you. We can read your lease agreement and tell you where you stand.
Know what your cargo policy covers before you need it
Bring your current policy, your broker requirements and a list of what you haul. We will go through it with you and show where the coverage is solid and where it is thin.