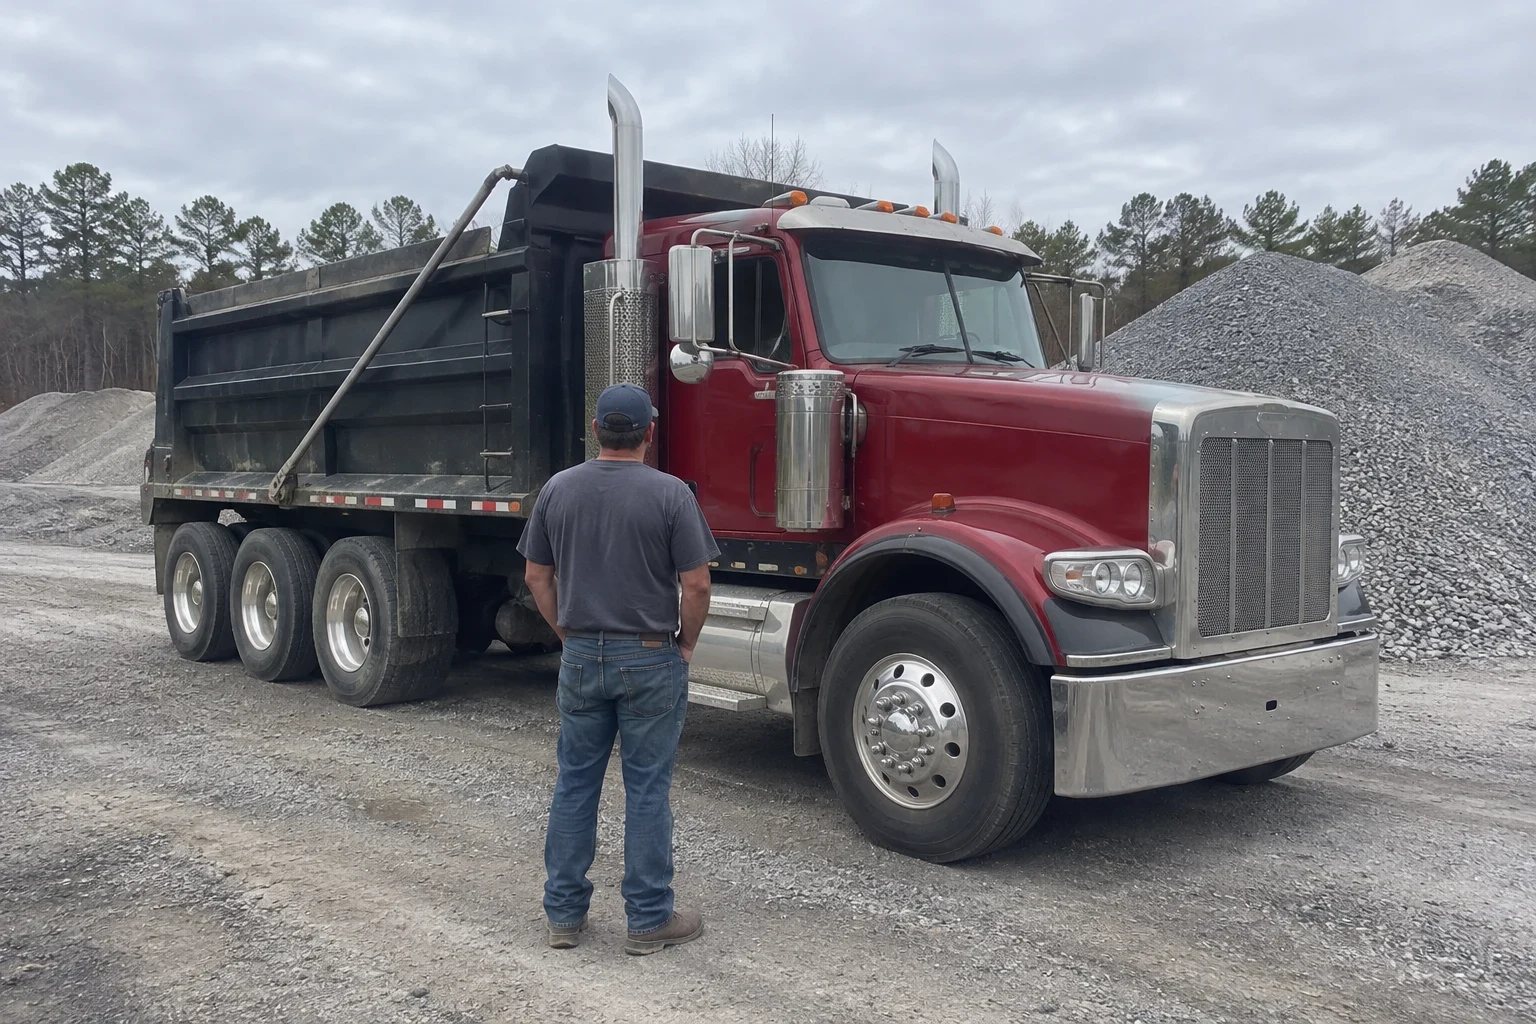
ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Marietta
Dump trucks earn their keep on rough ground: quarry scales, muddy site entrances, raised beds near power lines. We write coverage that reflects that work, with the haul radius, materials and equipment listed correctly, so the policy holds up when a claim lands.
Coverage built for trucks that work off the pavement
A dump truck policy looks like any commercial truck policy on paper. It has liability, physical damage and the filings your operation needs. The difference is in the details underneath. What you haul, where you load, how far you run from your yard and whether the truck is ever rented out with a driver all change how an underwriter sees the risk.
Most problems we see on construction truck policies start small. A truck rated for local hauling picks up work two counties further out. A new dump body is never added to the stated value. A general contractor needs specific wording on a certificate of insurance that the current policy cannot give. We spend the time to get those pieces right at the start, because fixing them after a loss is rarely possible.
We have been in business 5 years, and dump and construction truck owners around Marietta, Kennesaw and Woodstock are a steady part of the work we do.
What we set up on a dump truck policy
- Primary auto liability
- The coverage that answers for injury and property damage you cause on the road. We check the limit against what your contractors and any state or federal filings require, since many site jobs ask for more than the minimum.
- Physical damage for the truck and body
- Collision and comprehensive on the chassis, with the dump body, hoist and any added equipment included in the stated value. A truck covered at chassis value alone can leave a real gap after a rollover.
- Haul radius and commodity, listed accurately
- Sand, gravel, fill dirt, asphalt and demolition debris each rate differently. We record what you actually carry and how far you actually run, so the policy matches the work.
- Certificates for general contractors
- Job sites often ask to be named on your policy, along with waiver of subrogation or primary and noncontributory language. We review the contract request and tell you plainly what your policy can and cannot provide before you sign.
- Filings for your DOT number and authority
- If your operation needs state or federal filings, we make sure they are submitted and show correctly, so a missing record does not keep a truck off a job.
Signs your current coverage needs a closer look
Your hauls have gotten longer
A policy rated for short local runs may not fit regular trips well outside that radius. Underwriters treat distance as a real rating factor.
You added or replaced a dump body
New bodies, hoists and tarp systems add value. If the stated value was never updated, a total loss pays on the old number.
A contractor rejected your certificate
That usually means a missing endorsement or the wrong wording, not a missing policy. It is worth sorting out before the next bid.
You started hauling a new material
Moving from dirt and stone into asphalt or demolition debris can change how the policy should be written.
Nobody has explained your policy line by line
If you are not sure what is excluded or which drivers are listed, that alone is reason to review it.
What shapes your dump truck premium
Dump truck coverage is priced on risk, and construction work carries more of it than most highway freight. Several things move the number, and some are within your control. We walk through each one so the quote makes sense to you.
Truck value and equipment
Newer tri-axles and quad-axles with heavy bodies cost more to insure for physical damage than an older single-axle truck.
Drivers and experience
Years behind the wheel of a dump truck, along with clean driving records, matter a great deal. Newer drivers often raise the premium.
Radius and materials
Local hauling of aggregate rates differently from longer runs or debris work. Accurate answers here prevent problems at claim time.
Loss history and time in business
A few clean years help. A new venture or recent claims usually means fewer markets and a higher premium at first.
Limits and deductibles
Higher liability limits required by a contractor cost more, while a higher physical damage deductible can lower the premium.
How we put your coverage together
- 1
A conversation about the work
We meet at our office, or by phone or video, and ask about your trucks, drivers, materials, yard location and the contractors you work for. The more specific you are, the better the quote.
- 2
Gathering the right documents
Truck VINs and values, driver licenses, your DOT number and authority if you have them, and any loss history. If you have a contractor's insurance requirements, bring those too.
- 3
Shopping and comparing
We take your details to markets that write construction and dump truck risks, then lay the options side by side. You see the limits, deductibles and exclusions, not just the premium.
- 4
Binding, filings and certificates
Once you choose, we bind coverage, handle the filings your operation needs and issue certificates to the contractors on your list.
Questions dump truck owners ask us
Do I need cargo coverage for hauling dirt and gravel?
Often not, since loose aggregate has little value per load and many policies treat it differently. If you haul something with more value, or a contract asks for it, we can look at motor truck cargo insurance. We will tell you honestly whether it makes sense for your operation.
Why is dump truck coverage harder to place than regular trucking coverage?
Fewer carriers write it, and the ones that do look closely at rollover risk, job site conditions and driver experience. That is why accurate details matter so much. A clean, well-described submission gets better attention from underwriters.
My general contractor wants to be named on my policy. Can you do that?
Usually, yes, depending on the policy and the carrier. Share the contractor's requirements with us by phone and we will confirm which endorsements are available before you commit to the job. If something they ask for cannot be added, we will say so plainly so you can discuss it with them early.
I only haul inside Georgia. Do I still need filings?
It depends on how your operation is set up, the truck weights and whether you haul for hire. We will look at your situation and tell you which filings apply, then make sure they are submitted correctly.
Can I add a truck in the middle of the policy term?
Yes. Call us with the VIN, value and who will drive it, and we will add it and update your certificates so you can put it to work.
Let's go over your trucks and your jobs
Tell us what you haul, where you run and what your contractors need. We will put together coverage that fits the work and explain every line of it.