ServicesBox Truck Insurance
Box Truck Insurance in Marietta
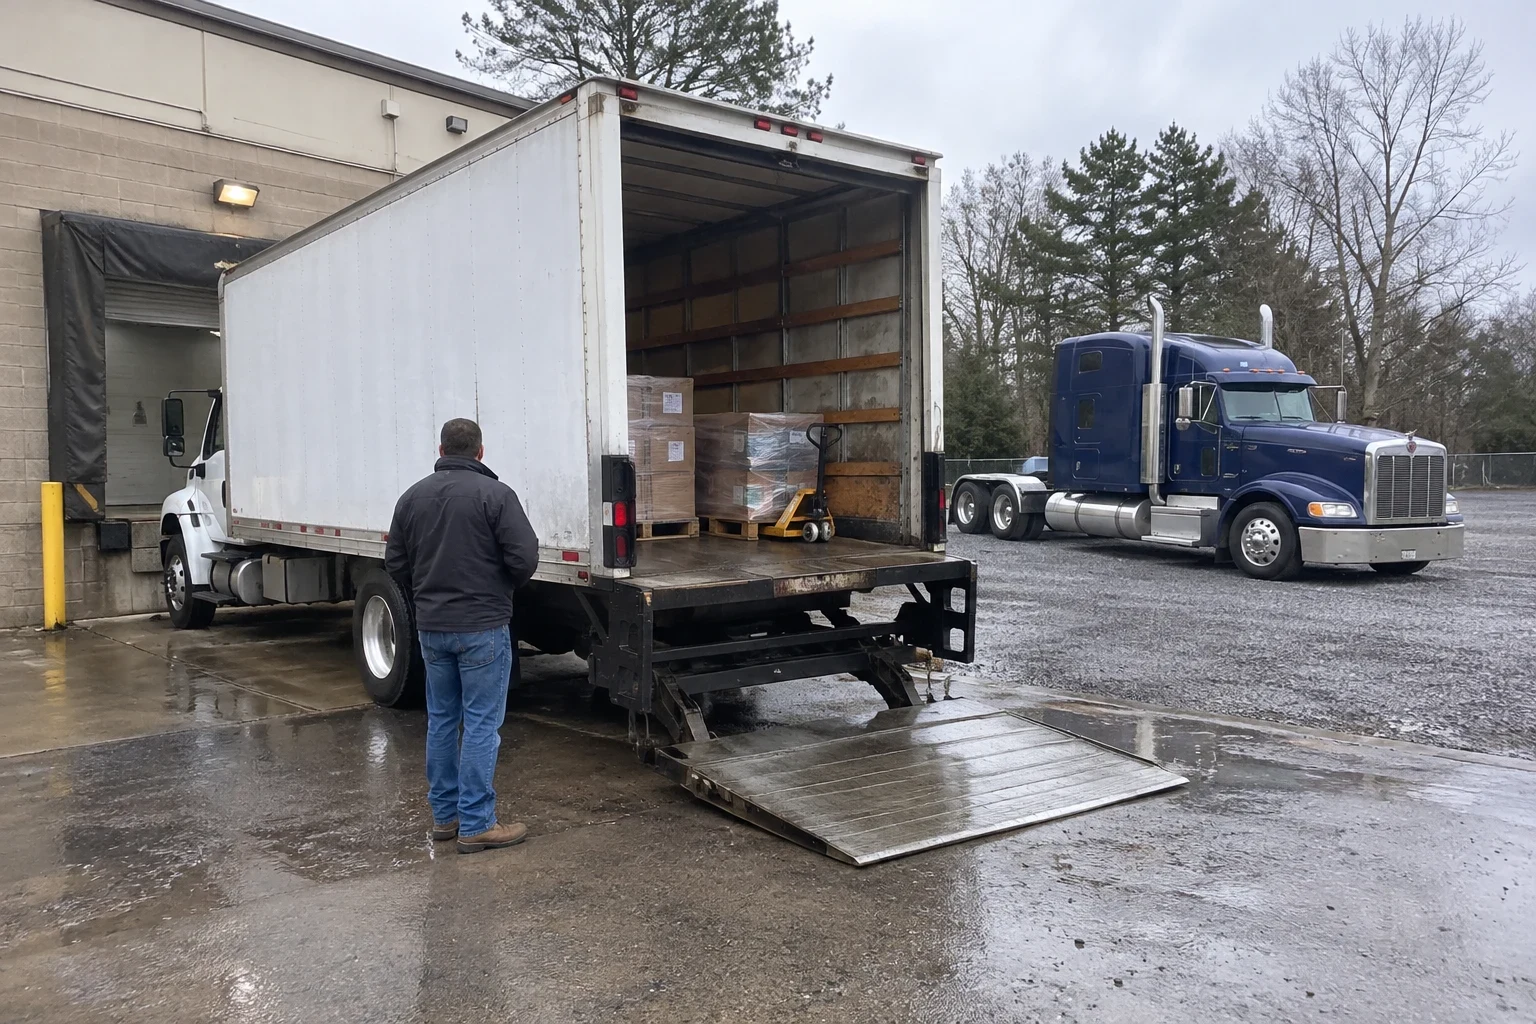
We insure box trucks for last-mile, freight and moving work, and we read the small print that decides whether a claim gets paid. The garaging address, the radius, the cargo you haul and the contract you signed all belong in the policy before your truck rolls.
Coverage built for how a box truck actually works
A box truck sits in an awkward middle. It is too big for a personal auto policy and often too small for the way a tractor-trailer policy is priced. Many operators run under 26,001 pounds without a CDL, yet still need a USDOT number, an MC authority for interstate for-hire work, and the filings that go with them.
Most box truck problems we see are not missing coverage. They are details written slightly wrong: a garaging address that no longer matches, a radius that stops short of the contract lanes, a cargo form that excludes the freight you carry most. We spend our time on those lines, because that is where a policy holds up or fails.
We have been in business 5 years, working with box truck operators from Marietta out to Kennesaw, Smyrna and Woodstock, by phone, video or at our office.
What a box truck policy usually includes
- Primary auto liability
- Covers injury and damage you cause to others on the road. We set the limit to match your authority and any broker or shipper contract, not just the legal floor.
- Physical damage
- Collision and comprehensive for the truck itself. We list the box body and liftgate at their real value so a roof strike or a liftgate failure is not undervalued at claim time.
- Motor truck cargo
- Protects the freight inside the box. We check the exclusions against what you haul, such as electronics, furniture or refrigerated loads, and look for unattended-vehicle conditions that catch drivers making multi-stop runs.
- General liability
- Covers incidents off the road, like a dolly scraping a customer's floor or damage at a loading dock. Many last-mile and delivery contracts require it alongside auto liability.
- Filings and certificates
- We handle the federal and state filings tied to your DOT number and MC authority, and we issue each certificate of insurance with the exact holder wording your shipper or broker asks for.
Signs your box truck coverage needs a closer look
Your contract changed
A new delivery contract often brings new limits, a requirement to name the shipper on your policy or a cargo minimum. If the policy was written before you signed, it may not meet the terms.
You added a liftgate or reefer unit
Equipment bolted on after the policy started is easy to leave off. A refrigerated box also needs its own breakdown coverage for spoiled loads.
Your runs got longer
A policy rated for local work may limit coverage outside a set radius. Regional runs need the radius to match.
A broker rejected your certificate
That usually means the limits, the business name on the policy or the holder wording do not line up. It is a quick fix once someone reads the full contract requirement.
You hired a driver
Every driver needs to be listed and accepted before they drive. An unlisted driver can turn a routine claim into a denied one.
What moves the premium on a box truck
Box truck premiums depend more on how the truck is used than on its size alone. We explain each factor plainly so the number on your quote makes sense. Small corrections, like an accurate radius or a cleaned-up driver list, can change it.
Cargo type
Furniture, appliances and electronics rate differently from dry general freight. High-theft or temperature-sensitive loads raise cargo costs.
Radius and lanes
Local runs usually rate lower than regional or interstate work. Metro traffic and the garaging location also play a part.
Driver history
Age, experience and motor vehicle records for every listed driver weigh heavily. A single new driver can move the premium more than the truck does.
Authority age
A new MC authority has no loss history yet, so early premiums tend to run higher. Clean years on record help at renewal.
Limits and deductibles
Contract-required limits set the starting point. Deductible choices on physical damage and cargo shift the balance between premium and out-of-pocket cost.
How we put your policy together
- 1
A conversation about your operation
We ask what you haul, where you run, who you contract with and how the truck is equipped. Have your DOT number, VIN and driver details handy if you can.
- 2
Reading your contracts
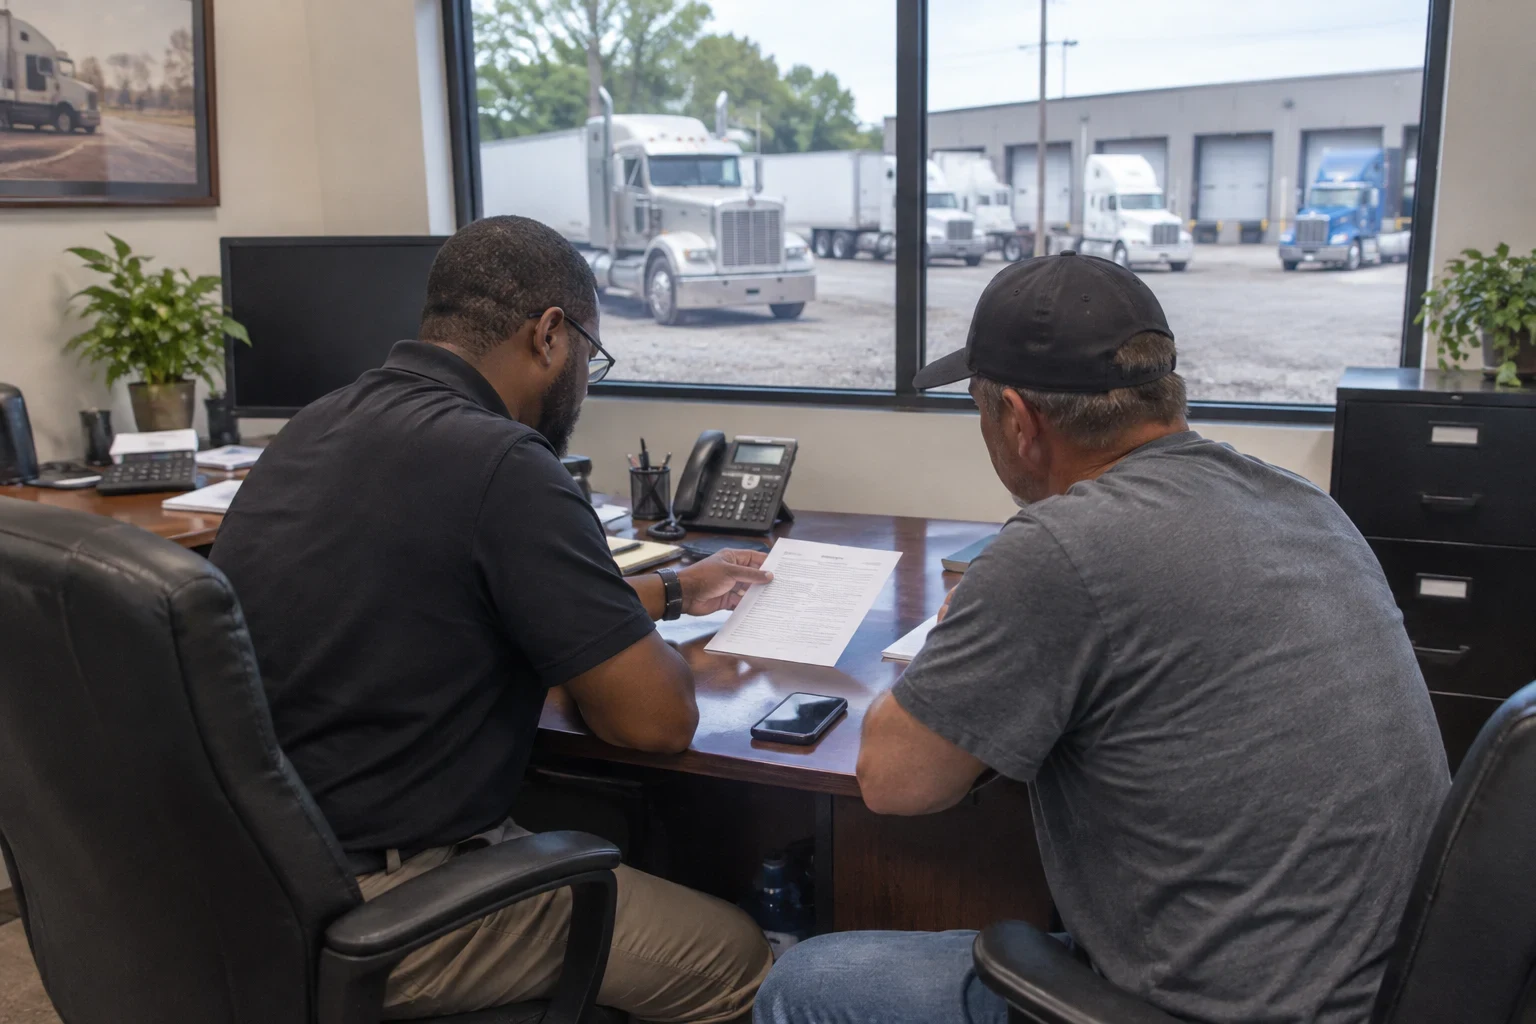
If a broker, shipper or delivery platform sets insurance terms, we go through them with you. Limits, endorsements and certificate wording all come from that document.
- 3
Quotes with the differences explained
We compare options and walk you through where they differ, including deductibles, cargo exclusions and radius terms. You see the tradeoffs before you choose.
- 4
Binding, filings and certificates
Once you decide, we bind coverage, file what your authority requires and issue certificates to the parties who need them. We note your renewal date and check in ahead of it.
Box truck insurance questions
Do I need my own authority to insure a box truck?
Not always. If you are leased on to a carrier, you may run under their authority and need non-trucking liability and physical damage instead. If you haul for hire under your own name across state lines, you need your own DOT number, MC authority and the filings that go with them.
Does my truck need commercial coverage if I don't have a CDL?
Yes, if you use it for business. A box truck under 26,001 pounds may not need a CDL, but personal auto policies exclude commercial hauling. The truck still needs a commercial policy.
Will my cargo coverage pay if the truck is broken into overnight?
It depends on the wording. Some cargo forms limit theft from an unattended vehicle unless it is locked, alarmed or parked in a secured lot. We read that clause with you and look for a form that fits how you park.
Can you meet the insurance terms for a delivery platform contract?
We work from the contract's stated requirements, including limits, general liability and any wording that names the platform on your policy. Walk us through the terms on a call or bring them to our office, and we will build the policy and certificates around them.
How long does it take to get a box truck quote?
It varies with the carrier and how complete your details are. Having your VIN, DOT number, driver information and contract terms ready makes the process much smoother.
Get the details right before the first load
Tell us about your box truck, your cargo and your contracts. We will go through the policy with you line by line and get your quote by phone.